
You’ve paid premiums for years. When disaster struck, your insurer should stand with you. Instead, you get a denial letter, a lowball check, or months of silence. Suli Law Group knows exactly how to compel property insurers to honor their contracts because of our past in the insurance industry.
Insurer Obligations Under Florida Law
Under Fla. Stat. § 627.70131, your insurer has the duty to do the following:
- Acknowledge your claim within 7 days
- Begin investigation within 7 days of proof of loss
- Conduct a residential physical inspection within 30 days of proof of loss
- Pay or deny the claim within 60 days
If your insurer pays more than 60 days after you report the claim, Florida law adds interest to the late payment, and missed deadlines may support a bad-faith claim in some cases.
Florida's Bad Faith Framework
Florida’s Civil Remedy Notice (CRN) statute allows policyholders to pursue insurers for unfair claim handling. Before filing a bad faith lawsuit, you must serve a Civil Remedy Notice through the Florida Department of Financial Services, giving the insurer 60 days to cure the violation.
A valid CRN must identify:
- The specific statutory provisions allegedly violated
- The facts and circumstances giving rise to the violation
- The names of individuals involved and the relevant policy language
If the insurer fails to cure within 60 days, you may pursue extracontractual damages beyond your policy limits, including consequential losses, attorney fees in some contexts, and even punitive damages in egregious cases.
For property insurance, Florida’s 2022 reforms (Fla. Stat. § 624.1551) added a critical prerequisite: bad faith requires adverse adjudication by a court that the insurer breached the contract. And since HB 837, mere negligence is no longer enough.
The Pre-Suit Notice Requirement
Before filing any property insurance lawsuit, Fla. Stat. § 627.70152 requires a Notice of Intent to Initiate Litigation at least 10 business days before suit. It must state what the insurer did wrong and, depending on the dispute, the amount in dispute and a settlement demand. Failure to comply means dismissal, and possible exposure to the insurer for attorney fees.
Common Insurer Violations
- Unreasonable delay in inspection or payment
- Unjustified denials based on weak engineering reports
- Misrepresenting policy provisions
- Demanding excessive documentation as a stalling tactic
- Lowball settlements unsupported by the actual scope of damage
Don’t let insurance companies get away with these tactics. Call Suli Law Group as soon as you receive a decision you believe is unjust.
Why Suli Law Group Is Different
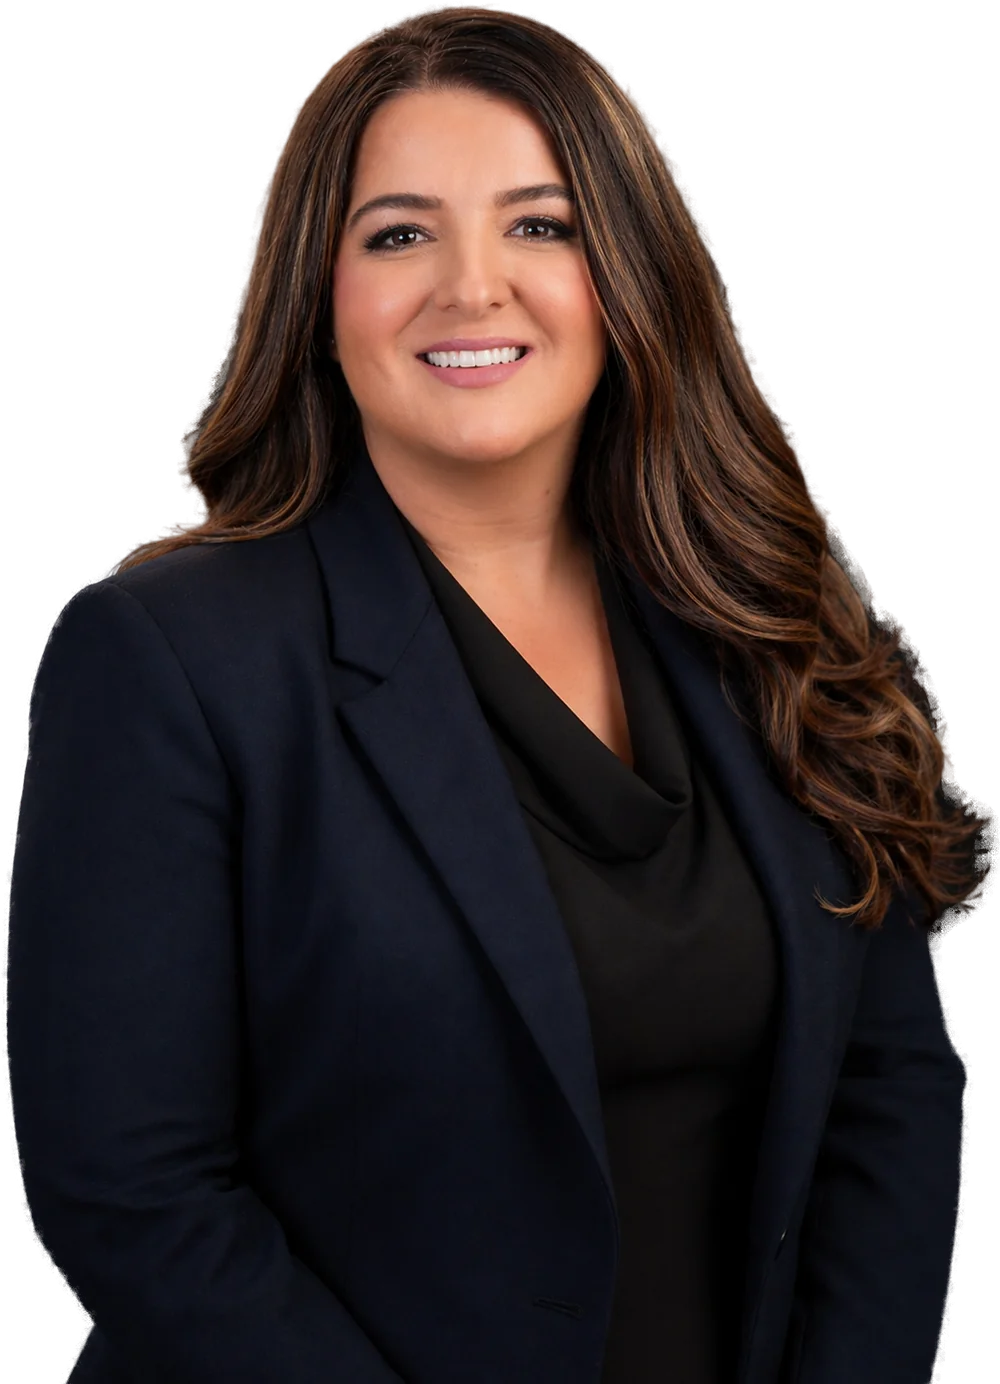
Founder and managing attorney Laura T. Sulisufay spent her early career on the insurance defense side. She knows how insurance claims work, what tactics insurers use, and the violations they commit. This past experience gives Suli Law Group the upper hand, ready to fight from the initial phone call to the final verdict.
Frequently Asked Questions
What deadlines does my insurer have to meet under Florida law?
Under Fla. Stat. § 627.70131, your insurer must acknowledge the claim within 7 days, begin investigating within 7 days of proof of loss, inspect a residence within 30 days, and pay or deny within 60 days. If your insurer pays more than 60 days after you report the claim, Florida law adds interest to the late payment, and missed deadlines may support a bad-faith action.
What is a Civil Remedy Notice (CRN), and do I need one?
A CRN is a required pre-suit filing through the Florida Department of Financial Services that gives your insurer 60 days to cure the violation before you can sue for bad faith. It must identify the statutes violated, the facts behind the violation, and the people and policy language involved.
How did Florida's recent reforms change bad faith claims?
For property insurance, bad faith now requires a court to first find that the insurer actually breached the contract. Mere negligence is no longer enough.
Do I have to do anything before filing an insurance lawsuit?
Yes. Fla. Stat. § 627.70152 requires a Notice of Intent to Initiate Litigation at least 10 business days before suit, stating what the insurer did wrong and, depending on the dispute, the amount in dispute and a settlement demand. Failure to comply may result in dismissal.
Why does Suli Law Group have an edge against insurers?
Founder and managing attorney Laura T. Sulisufay spent her early career on the insurance defense side, so she knows the tactics carriers use and the violations they commit. That insider experience lets the firm fight effectively from the first phone call through the final verdict.